9 gigacasting technologies to watch 2027
Gigacasting is manufacturing by subtraction. When Tesla brought its first Idra Giga Press online at Fremont in 2020, the machine closed its die with roughly 5,600 to 6,200 tonnes of force and turned Model Y underbody assemblies of up to 70 stamped and welded parts into two or three castings. Every part that disappeared took its welds, its robots and its share of floor space with it.
That first round of savings came from the press. Judging by what companies have patented since the start of 2024, the next round will come from everything around it. Carmakers and their suppliers are patenting ways to drop the heat-treatment furnace, to cast crash parts from scrap, to fold the battery tray into the floor, to use one die for several models, and to fill parts larger than a single injection shot can reach. Repair is the exception. The patents describe ways to keep a crash away from the casting, while the question of how to fix a damaged one stays open.
On the ITONICS automotive trend radar, gigacasting is rated a high-impact trend for the next two to four years, with repair cost as its hidden trade-off. ITONICS AI, Prism, analyzed 428 patent families on large structural die casting, all first filed since January 2024, and grouped them by the step each one removes.
The nine gigacasting technologies to watch in 2027 are listed in Exhibit 1:
| Technology | Families | What it deletes | Who is building it |
| 1. Heat-treatment-free structural alloys | 173 | The heat-treatment furnace and the straightening that follows it | Guangdong Huihuang, BYD, Xiaomi, Volkswagen, Honda, Tesla |
| 2. Recycled-content and iron-tolerant alloys | 35 | Primary aluminium in crash-relevant parts | Magna, Tesla, Novelis, Bocar, Hunan University |
| 3. Magnesium large castings | 28 | About a third of the part's mass versus aluminium | FAW, Xiaomi, Changan, Shanghai Jiao Tong University, Shanxi Regal |
| 4. Melt-to-die integration and high vacuum | 13 | Gas and oxide pick-up between furnace and die | Shuaiyichi, Changan, FAW, Minglida, South China University of Technology |
| 5. Zone-level die thermal control | 8 | The hot spots behind porosity and scrap | Ningbo Asiaway, Dongfeng, Minglida, Harbin Institute of Technology |
| 6. Multi-variant and multi-piece dies | 8 | The die built for one part on one model | Dongfeng, Changan, Jiangsu Tianhong, EVE Energy |
| 7. Multi-injection presses and dies | 8* | The size limit of a single injection shot | LK Technology, Chery, Hefei University of Technology, Chongqing Guangcheng Mould |
| 8. Steel-aluminium hybrid castings | 19 | Separate steel reinforcements and their joints to the casting | Hangyu Zhizao, Dongfeng, FAW, NIO, Martinrea |
| 9. Cast battery enclosures and cell-to-body lower bodies | 33 | The welded battery tray as a separate structure | Toyota, BYD, Chery, Ford, Nemak, Martinrea |
Exhibit 1: Gigacasting technologies to watch in 2027
Most of the new ideas are in the metal. Two in five patent families deal with aluminium alloys that need no heat treatment after casting, and 17 carmakers have filed alloy recipes of their own, among them BYD, Xiaomi, Li Auto, Volkswagen, Honda and Tesla. The die-casting machine is the subject of only one family in twenty. For casting suppliers, this shift matters, because a carmaker that owns the alloy also decides who is qualified to cast it.
The newest patents make the die more flexible. A gigacasting die is normally built for one part of one model, so every model change means new tooling. Since 2025, filings have started to tackle that with dies that serve several models, cooling controlled zone by zone, and two injection systems feeding one cavity. The eight families on multi-model dies were all filed from April 2025 onwards; the eight on zone-by-zone cooling from September 2025.
China files more than nine in ten die-casting patents. The share is measured on the patent classes for die casting, which makes it independent of wording and language. Outside China, filing clusters around two topics. Toyota, Ford, Nemak, Magna and Martinrea work on cast battery enclosures; Volkswagen, Honda, Tesla, Magna and Novelis on alloys.
Exhibit 1 lists the nine technologies in the order a gigacast is made, from the metal to the finished part, together with what each one removes.
These three change what a gigacast is made of. Alloy patents alone make up two in five families in the corpus.
What it is. A heat-treatment-free structural alloy is an aluminium casting alloy that is strong and ductile enough for crash-relevant body parts straight out of the die. The part skips the heat treatment that structural castings usually need.
Volkswagen and Audi filed three families on an alloy for structural castings in October 2024 (EP 4729645 A1, EP 4729646 A1, EP 4793376 A1). Honda filed with the die caster Ryobi on a ductile Al-Si-Mg alloy that also sticks less to the die (WO 2025/192182 A1), and Xiaomi on an aluminium-magnesium alloy tuned for bending (CN 118291824 B).
What changes. The idea predates the giga press. Rheinfelden developed Castasil-37 for large structural castings used as cast, and Tesla patented its own structural alloys in 2017 and 2020 (US 11421304 B2, ES 3004343 T3). Today carmakers write these recipes themselves, where they used to buy them from an aluminium supplier's catalogue, and since 2025 aluminium-zinc and aluminium-magnesium grades have joined the familiar aluminium-silicon ones. Skipping heat treatment saves the furnace and the straightening a distorted rear floor would need.
Who is building it. 173 families from 92 companies and institutes, led by Guangdong Huihuang with 20. Seventeen carmakers file, and about one family in ten comes from outside China, mostly from Volkswagen, Honda, Tesla, Magna and Novelis.
What to watch. Licensing. Shared alloy patents could turn a few recipes into industry standards. Captive ones let each carmaker choose which foundries may bid for its parts, and casting suppliers should price that dependency into their contracts.
What it is. A recycled-content structural alloy is a die-casting alloy that copes with the iron, zinc, and copper in scrap, so crash-relevant parts can be cast from secondary aluminium.
Tesla's newest casting patent describes an alloy made largely from scrap, with indices for hard phases and sludge that keep strength and ductility in range (WO 2025/259916 A1, first filed June 2024). Magna holds three families on a secondary alloy for structural parts (WO 2025/147523 A1, WO 2025/147527 A1, EP 4772660 A1), and Novelis claims recycled alloys for large car parts that tolerate zinc (WO 2025/165574 A1).
What changes. Recycled aluminium has gone into engine blocks and gearbox housings for decades. Crash parts stayed with primary metal because iron from scrap forms brittle particles that cut elongation. These patents go after that limit. For a part the size of a floor, the alloy sets much of the metal cost and the carbon footprint.
Who is building it. 35 families from 27 applicants, with four at most per applicant. One in five comes from outside China, more than in any other alloy topic, from Tesla, Magna, Novelis, Bocar and UT-Battelle. The share of filings held steady at about a tenth in 2024 and 2025.
What to watch. A carmaker that requires a minimum share of recycled aluminium in a structural casting. Tesla's 2024 patent reads like groundwork for it, and the supplier that qualifies a secondary-based alloy first is likely to set the benchmark grade.
What it is. Magnesium large casting means making body-sized parts such as floors, shock towers or battery boxes from magnesium, with alloys and processes that handle its flammability, corrosion and lower ductility.
FAW holds four families, from a heat-treatment-free, corrosion-resistant magnesium alloy (CN 118272711 A) to friction stir welding for a cast magnesium battery box (CN 119057202 A). Xiaomi has a magnesium alloy for structural parts (CN 120174246 B), Shanxi Regal flame-retardant alloys (CN 120888821 B), and the Harbin Institute of Technology forming equipment for a magnesium rear floor (CN 121835013 A).
What changes. Cars have used die-cast magnesium for decades in instrument panel beams, seat frames and steering wheel cores, all mid-sized parts away from crash and corrosion zones. The new patents go after the body and after the weaknesses that kept magnesium out of it: fire risk, galvanic corrosion and low elongation. Magnesium weighs about a third less than aluminium for the same volume, so a magnesium floor would be the next step down in mass.
Who is building it. 28 families from 20 applicants, three in four of them filed in 2025 or later. FAW and Shanghai Jiao Tong University have four each. All applicants are Chinese, including the carmakers FAW, Xiaomi, Changan and BYD.
What to watch. A magnesium body casting in a production car, and a first applicant from outside China. China dominates primary magnesium supply, so carmakers elsewhere will meet this technology first as a supply-security question.
Between the furnace and the finished part sit the molten metal and the die. These three technologies aim at the two figures that decide a casting plant's economics, scrap rate and tooling cost.
What it is. Melt-to-die integration covers the equipment between furnace and die that keeps gas and oxides out of the metal, from direct supply of molten aluminium and inline degassing to vacuum systems that empty the die and check it for leaks.
Shuaiyichi feeds new and recycled molten aluminium straight into an integrated die-casting cell (CN 119772136 A) and degasses it inline (CN 223723183 U). Changan has its own system for conveying molten aluminium (CN 121423566 A). Sichuan Shundiwei patented a quick leak test for large vacuum systems (CN 122045679 A), and South China University of Technology keeps the metal under vacuum from melting to casting (CN 122441913 A).
What changes. Vacuum die casting and degassing are standard foundry practice. Gigacasting raises the stakes, because a single shot holds far more metal and one porous area scraps the whole part. Tesla filed on immersion melting of aluminium in 2023 (WO 2025/064898 A1). Quality control is moving upstream, from checking castings to preparing the melt.
Who is building it. 13 families from 12 applicants, eight of them filed since December 2024. Two carmakers, Changan and FAW, file on melt handling themselves.
What to watch. Liquid aluminium delivered to casting plants under supply contracts, and leak monitoring as standard on gigacasting cells. For scrap rates, the route from furnace to die is becoming as important as the press.
What it is. Zone-level die thermal control adjusts the temperature of a gigacasting die area by area, with separate cooling circuits, conductive inserts at hot spots and sensor-based control.
Ningbo Asiaway filed two families in June 2026, one on partitioned cooling channels (CN 122322440 A) and one on highly conductive inserts for hot spots (CN 122327227 A). Dongfeng controls temperature zones in very large dies (CN 122343252 A), and Minglida balances die heat and vacuum together (CN 121244898 A).
What changes. Dies have always been cooled, and conformal channels in 3D-printed inserts are well established. A die the size of a car floor spans thin flanges and thick nodes, though, so a single cooling setting leaves some areas too hot and others too cold. Hot spots are where shrinkage porosity starts. These patents give each zone its own control loop.
Who is building it. Eight families from seven applicants, all filed from September 2025 onwards. Dongfeng is the only carmaker, and all applicants are Chinese.
What to watch. Press and die makers selling zone control as a standard package with guaranteed scrap rates. For casting suppliers, die temperature is becoming the main lever behind the scrap rate they quote, and behind their margin.
What it is. A multi-variant gigacasting die serves more than one part or vehicle model, for example a die that casts two parts per shot or a standard casting with adapter interfaces.
Dongfeng's modular rear floor is a standard casting with adjustable adapters, and the patent names the problem plainly: integrated die-cast parts are model-specific and costly to carry across platforms (CN 121341292 A). Dongfeng also casts its front cabin as two pieces in one die (CN 122378067 A). Changan casts several body parts in one die (CN 121892649 A), and Jiangsu Tianhong has a modular casting system for several vehicle types (CN 120696387 A).
What changes. Multi-cavity dies are routine for small castings. Large body parts went the other way, with one die for one part on one model, which turned every facelift into a tooling decision. These patents treat the large casting as a platform part.
Who is building it. Eight families from five applicants, all filed since April 2025. Carmakers lead, with Dongfeng at three and Changan at two, and all applicants are Chinese.
What to watch. A production car that shares a cast floor or front cabin with a sister model. Carmakers planning gigacasting should ask suppliers for die-sharing concepts before they order a single-model tool.
The press started the gigacasting story, yet only one patent family in twenty concerns the machine itself. One development there is worth following, because it changes how presses grow.
What it is. Multi-injection die casting fills one cavity from two or more synchronised injection units, so the metal travels a shorter distance and the flows meet in a controlled zone.
LK Technology, which has owned Idra since 2008, filed three dual-injection families in China, the US and Japan, among them a synchronised dual injection system (EP 4650082 A1, first filed May 2024). Chery fills a battery housing from two injection points (CN 119857838 A), and Hefei University of Technology controls the zone where the two metal flows meet (CN 122538748 A).
What changes. Since 2018, presses have mainly grown in clamping force. Idra took the first order for its 5,500-tonne machine that year and now builds presses of up to 9,000 tonnes. A single shot still has to push all the metal through one gating system before the thinnest walls freeze. A second, synchronised shot shortens that path but creates a seam where cold shuts and oxide films can form, which is why Hefei's patent on that zone matters.
Who is building it. Eight families from six applicants, half of them filed in 2025 or later, plus LK's three families outside China. Chery is the only carmaker.
What to watch. A multi-injection press in series production. Buyers planning the next press generation should check whether their future parts need more tonnes or more shots.
The last two technologies change the part itself. One puts steel inside the casting, and the other turns the casting into the battery housing.
What it is. A hybrid casting combines cast aluminium with steel or formed profiles, either cast in during the shot or joined afterwards, so crash loads run through the wrought material.
Hangyu Zhizao, a Beijing engineering firm, holds seven families, among them A- and B-pillar tubes shaped by hot-gas forming and then cast into aluminium (CN 119549574 A). Dongfeng filed three in 2025 that embed steel inserts in a cast front cabin, side wall and rear floor (CN 120552969 A, CN 120621504 A, CN 120534437 A). FAW casts a subframe around a hollow profile (CN 118270112 A), and Martinrea joins castings by overmoulding them with structural plastic (WO 2026/193136 A1).
What changes. Cast-in inserts are old; aluminium engine blocks have carried iron cylinder liners for decades. Here the insert carries crash load. A steel tube in a cast pillar adds strength where it is needed and lets the casting get smaller, which eases both the alloy's elongation limit and the size of the die.
Who is building it. 19 families from ten applicants. Hangyu Zhizao has seven and Dongfeng three, and the carmakers Dongfeng, FAW, NIO and Toyota all file.
What to watch. A production body with steel cast into a gigacast part. For steelmakers and tube formers, these patents mark a way back into the body structure.
What it is. A cast battery enclosure is a battery tray or lower housing made from one or a few die castings. In the cell-to-body version, the cast lower body carries the cells directly and becomes the vehicle floor.
Nemak patented a die-cast battery carrier (EP 4585325, first filed January 2024), Ford a cast battery carrier for electric vehicles (US 2026/0088426 A1), and Toyota a cast lower battery case filed in five countries (KR 20250110167 A). GAC Honda has a manufacturing method for a CTB lower body (CN 118832018 A).
What changes. Battery trays have typically been welded together from aluminium extrusions and sheet. A cast tray integrates cross members, mounts and cooling channels and removes most of the welds a sealed housing depends on. Cell-to-body removes the tray altogether, so one casting carries crash loads and battery loads.
Who is building it. 33 families from 23 applicants, nine of them carmakers. A quarter come from outside China (Toyota, Ford, Nemak, Magna, Martinrea), and one in five is filed internationally, more than for any other technology here.
What to watch. Who wins the casting work: suppliers such as Nemak, Magna and Martinrea, or carmakers such as BYD and Chery that patent ways to cast the floor themselves. For insurers, an enclosure cast into the floor ties battery replacement to body repair.
Four more topics are worth following. One is the established core of gigacasting, two are still small, and the fourth is the factory Toyota is building around the casting.
Integrated body modules: established, with a shrinking share. Cast rear floors, front cabins and underbodies are the classic gigacasting parts. They account for 60 patent families, 15 carmakers file on them, and 14 of the families come from outside China. Volvo has a cast rear structure with a plate segment fastened to it (US 2026/0285404 A1), Hyundai and Kia an integrated casting in the front body (US 2026/0274346 A1), and the Korean supplier Dongseo a centre underbody made by large-scale die casting (KR 20260083588 A). Their share of new filings fell from 12% in 2024 to 9% in 2025, as inventive work moved upstream to alloys, dies and process. Watch this area for production launches.
Simulation-led casting design: steady. 33 families cover topology design, property prediction and process optimisation, with Hunan University and Dongfeng doing the most. General Motors contributes an unusual idea, a sand-cast prototype with the material properties of a high-pressure die casting (US 2025/0262659 A1). It lets engineers test a design before the die is built.
Dimensional control of as-cast parts: early. Four families aim to deliver gigacasts within tolerance and skip the straightening step: Dalian University of Technology's straightening-free casting (CN 120485605 A), Jiaxing Lishi's shape-correcting device (CN 119897380 A), FAW's method for setting tolerances on a cast floor (CN 121706230 A) and Wencan's correcting die for a battery box cover (CN 121017382 A). Toyota adds two families on preventing distortion in die castings (JP 2026048405 A, JP 2025133535 A). The numbers are small. They fit the pattern of the alloy patents, though, where removing heat or handling also removes distortion.
Toyota's self-driving assembly line. A search of patent descriptions turns up 74 Toyota families that take gigacast body modules as the starting point for vehicles that drive themselves through the plant, through inspection and assembly, under remote control. 43 of them are filed in China, Europe, Japan and the US at the same time. They are production-system patents, and they show where Toyota expects gigacasting to lead: a body that arrives as a few large modules and moves itself down the line.
Each of the nine technologies removes something from the process, and repair is the step left standing. Four of the 428 patent families reduce repair costs by design. A method for repairing a damaged gigacast is missing from the patent record altogether.
Dongfeng holds three of the four. The first sets a crash-load hierarchy in which the crash box gives way before the longitudinal beam, and the beam before the cast front cabin (CN 120493398 A). The second builds the body from modular castings to cut maintenance costs after a collision (CN 121404372 A), and the third bolts detachable cross members onto a universal cast rear floor (CN 120207449 A). A utility model from Qingdao Haozhou adds a detachable crash beam for an integrated die-cast body (CN 224576587 U). Repair does show up in the patents, for the tooling: Minglida rebuilds very large dies with additive welding (CN 121199287 A, CN 119328146 A), and Volkswagen has a method for repairing casting tools (DE 102024202071 A1). The die, in other words, has a repair process, while the car relies on designs that keep crash forces away from the casting.
Repair methods could be filed in body-repair classes outside our searches, or documented in workshop manuals instead of patents. Even so, the gap is a clear signal. It confirms the trade-off flagged on the ITONICS automotive trend radar: a damaged gigacast gets replaced as a whole.
Three groups should act on that in 2027:
Carmakers face three decisions at once. Should they own the alloy? Should the next die serve one model or several? Does the next press need more tonnes or more shots? The patents show Chinese carmakers answering all three in-house.
Casting and materials suppliers are dealing with carmakers that patent their own alloys and their own melt handling. Their strongest position in this corpus lies in the process: zone-level die control, vacuum and melt quality, recycled-content alloys and cast battery structures. Battery structures are also the one area where Nemak, Magna and Martinrea file alongside the carmakers.
Insurers and fleet owners should assume that structural damage to a gigacast vehicle means replacing the whole part, and that body repair and battery replacement are linked wherever the enclosure is cast into the floor. Both belong in residual value estimates.
Read together, the nine technologies move the decisive questions in gigacasting away from the press. The first wave was about buying the largest machine. The next one is about owning the alloy, controlling the melt and the die, and designing castings that serve more than one model. Most of this engineering happens in China, and a large part of it is filed by carmakers themselves.
The filings behind this watch were first made in 2024 and 2025 and are being published now. That makes 2027 the year in which it becomes visible which of them reach production, and who supplies them.
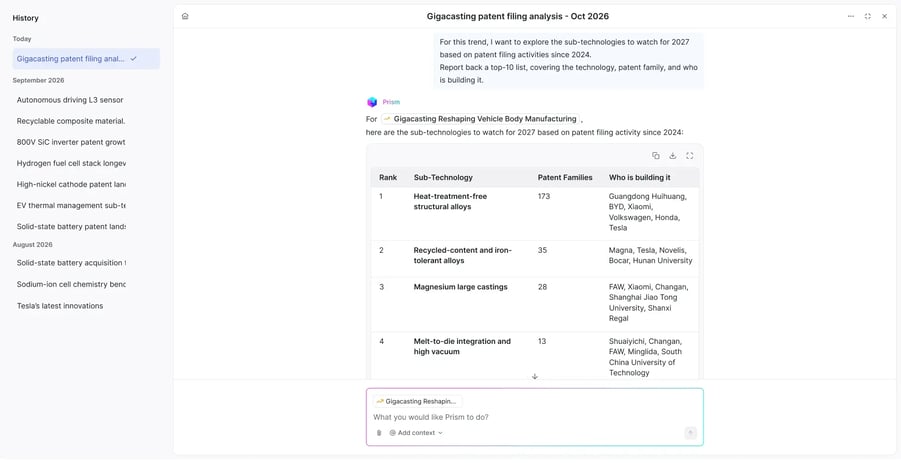 Exhibit 2: Prism detecting gigacasting technologies to watch in 2027
Three groups should act on this in 2027.
Carmakers face three decisions at once. Should they own the alloy? Should the next die serve one model or several? Does the next press need more tonnes or more shots? The patents show Chinese carmakers answering all three in-house.
Casting and materials suppliers are dealing with carmakers that patent their own alloys and their own melt handling. Their strongest position in this corpus lies in the process: zone-level die control, vacuum and melt quality, recycled-content alloys and cast battery structures. Battery structures are also the one area where Nemak, Magna and Martinrea file alongside the carmakers.
Insurers and fleet owners should assume that structural damage to a gigacast vehicle means replacing the whole part, and that body repair and battery replacement are linked wherever the enclosure is cast into the floor. Both belong in residual value estimates.
This analysis uses Filing Signal Analysis, which treats the decision to file as the signal. Drafting and prosecuting a patent application costs real money, so every filing stands for R&D spend a company has already committed. Applications are published about 18 months after they are first filed. Families first filed in 2025 and 2026 are therefore still coming in, and to keep that delay from looking like a decline, we compare each technology's share of the 2024 filings with its share of the later ones, leaving out Chinese utility models because they publish faster.
Prism screened 7,000 patent families from four searches and kept 428 that concern large structural die casting. A patent family is one invention, counted once however many countries it is filed in. The data comes from lens.org, extracted on 8 October 2026, and covers inventions first filed from 1 January 2024 in all jurisdictions, China included. The four searches looked for gigacasting and heat-treatment-free die-casting terms in titles, abstracts and claims; the die-casting patent classes B22D17 and B22D21/007; the aluminium and magnesium alloy classes C22C21 and C22C23 where die casting appears in the full text; and gigacasting terms used only in a patent's description, which is where Toyota's factory patents turned up.
Each family was screened by hand on its title and abstract. About half of the raw keyword results passed, because "integrated die casting" also describes one-piece street lamps, faucets and wheelchair frames. The class searches close a language gap. English keywords miss Chinese patents published only in Chinese, and the search by international patent class (IPC) also catches Chinese utility models, which rarely carry a CPC code. Applicants are counted as groups, with subsidiaries merged into their parent.
A company missing from these results may file under other classes, describe its work in other terms, or keep it as a trade secret. Its absence here is a filing signal and should be read as one.
The technologies that will define your market in 2027 are already documented. ITONICS Prism finds and reads them for you. Prism reads 500M+ patents and scientific publications and connects to the Web in real-time. It uses your individually defined context and configurable AI agents to work on the questions your team actually needs answered:
ITONICS is the #1 operating software for innovation and R&D management. It helps innovation and R&D leaders identify emerging technologies, prioritize investment opportunities with evidence, and steer execution across business units.
Recognized by Gartner in four innovation categories in the Hype Cycle for Innovation Practices, ITONICS supports over 500 companies worldwide, including Amazon, adidas, Johnson & Johnson, Toyota, Mondelez, and Siemens.